Screenshots show the built-in sample plan — your numbers will look different, but the layout is the same.
Getting Started
Your first five minutes with RetireTaxGuide — what to do before anything else.
What is RetireTaxGuide?
A fully private, browser-based retirement planner. You answer questions about your household, accounts, income, and spending — then it projects your finances year-by-year through retirement, calculating real federal taxes, Social Security, RMDs, and Medicare surcharges. No sign-up, no server, no data leaves your device.
The 5-step quick start
Go to Plan Setup in the sidebar. Work through all 7 steps — Household, Persons, Assumptions, Accounts, Incomes, Expenses, Review. Takes 10–15 minutes.
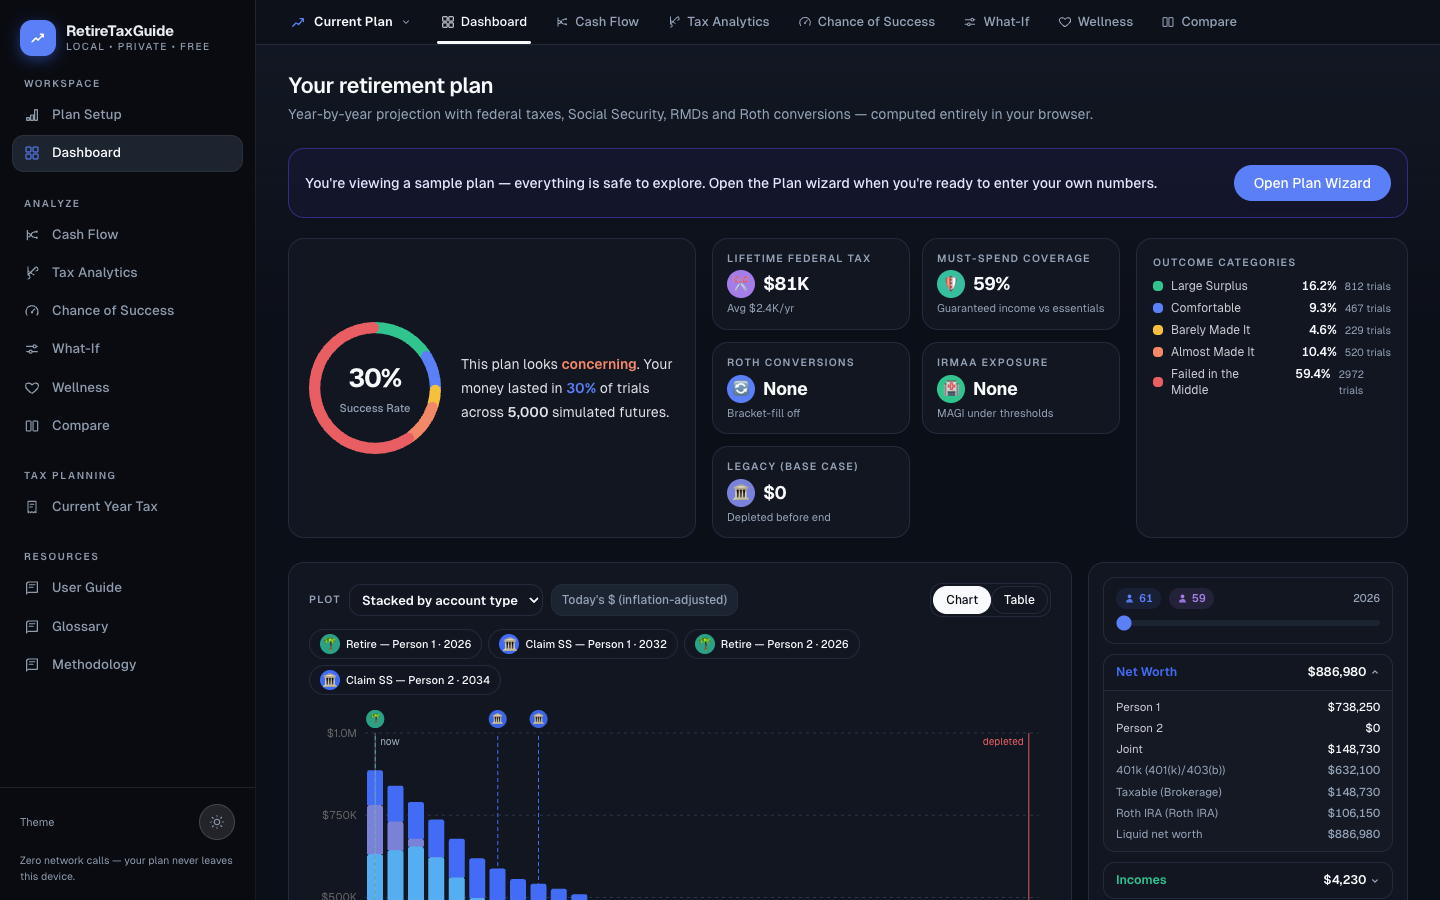
After the wizard, you land on the Dashboard. Look at the verdict band, main chart, and yearly summary sidebar. Make sure the numbers look reasonable.
Click "Run Monte Carlo" in the verdict band. This runs 5,000 randomized scenarios and shows your true chance of success.
Use Cash Flow to see where money goes each year. Use Tax Analytics to understand your lifetime tax burden.
The Current Year Tax planner is a sandbox. Drag sliders and see how taxes, IRMAA, and ACA respond instantly.
Understanding the layout
Sidebar: Workspace holds Plan Setup and Dashboard; Analyze holds Cash Flow, Tax Analytics, Chance of Success, What-If, Wellness, and Compare; Tax Planning holds Current Year Tax; Resources holds this guide and the Methodology page. On mobile the same menu opens from the hamburger button.
Plan tabs: On Dashboard and Analyze pages, a horizontal tab bar lets you jump between views, with a dropdown for switching between your current plan and saved scenarios.
Theme toggle: Every page offers light and dark mode. Screenshots in this guide were taken in dark mode.
Key concepts
Base case vs. Monte Carlo: The base case is one projection using your assumed returns. Monte Carlo runs thousands of randomized scenarios to show the range of possible outcomes — a plan can look fine in the base case yet fail often under randomness.
Today's dollars vs. nominal: Charts can show inflation-adjusted (today's) dollars, which are easier to relate to current spending, or nominal future dollars, which is what statements will show.
Guardrails: Spending bands tied to success probability — above 95% you could spend more, around 80% you are on target, below 70% consider cutting back.
Saved scenarios: Up to 10 what-if snapshots you can compare side-by-side and load onto any page.